This report is powered by Tridge Eye Data Intelligence.
Every data point, price signal, and supply risk insight in this analysis comes from the same platform that procurement and sourcing leaders worldwide rely on daily. As you read, consider what this level of market intelligence could do for your sourcing decisions.
This playbook is written for procurement leaders who already run professional sourcing processes, but don’t live in sunflower oil every day. The goal is practical: reduce landed-cost variance and disruption exposure by separating what’s truly “market” (feedstock) from what’s supplier-controlled (processing, logistics, and allocation premiums).
Analyzed at: Apr, 2026
Insight: Treat current negotiations as a premium transparency exercise more than a pure “market down/up” debate. The vegetable-oil complex has been firm into early 2026 (supporting suppliers’ confidence), while sunflower oil itself can still decouple versus the complex depending on Black Sea/EU flows and product mix. [1] Your best near-term lever is to (1) force itemized premiums (refining/dewaxing, HO, and corridor adders), (2) cap or index those premiums with clear reopeners, and (3) activate at least one alternate corridor/supplier before freight/insurance shocks turn into allocation. Also document benchmark methodology/basis changes in your pricing files so you don’t misread normalization as a true market move. [2]
Access the live market signals behind this analysis.
Insight → Sunflower oil rarely “tracks” sunflower seed in a clean, linear way. Most procurement teams lose money in the gaps: when crude vs. refined spreads widen, when high‑oleic premiums spike independently, and when freight/insurance/basis moves overwhelm the headline commodity.
Data → In practice, procurement sees sequences like: seed down mid‑single digits, crude flat, refined up—because refiners are protecting margins, inventory was bought earlier, and logistics premiums reprice faster than product lists. Market methodologies themselves can shift (e.g., assessment basis changes), creating apparent “price moves” that are actually normalization effects. [2]
Procurement impact → Your alpha comes from:
Quick win this week: Rebuild your negotiation sheet into three lines (feedstock/index proxy + processing premium + logistics/basis) and set trigger bands for when to switch from spot to short‑term coverage.
Insight → The biggest mistakes happen when you assume upstream (seed/crude) and downstream (refined/packed) prices move together. They don’t. Sunflower is a margin-managed chain: crushers/refiners defend utilization and cashflow, and they reprice with lags.
Data → Three recurring disconnect patterns show up in real buying cycles:
| Component that disconnects | Typical move when it bites | What suppliers will call it | What you should call it |
|---|---|---|---|
| Refining + dewaxing premium | +$40 to +$120/MT | “Processing cost increase” | “Margin reset—show me drivers” |
| Freight/insurance/basis | +3% to +7% landed | “Logistics volatility” | “Corridor premium—quote it separately” |
| High‑oleic premium | +10% to +20% vs standard (can spike) | “HO tightness” | “Identity-preserved scarcity—prove allocation” |
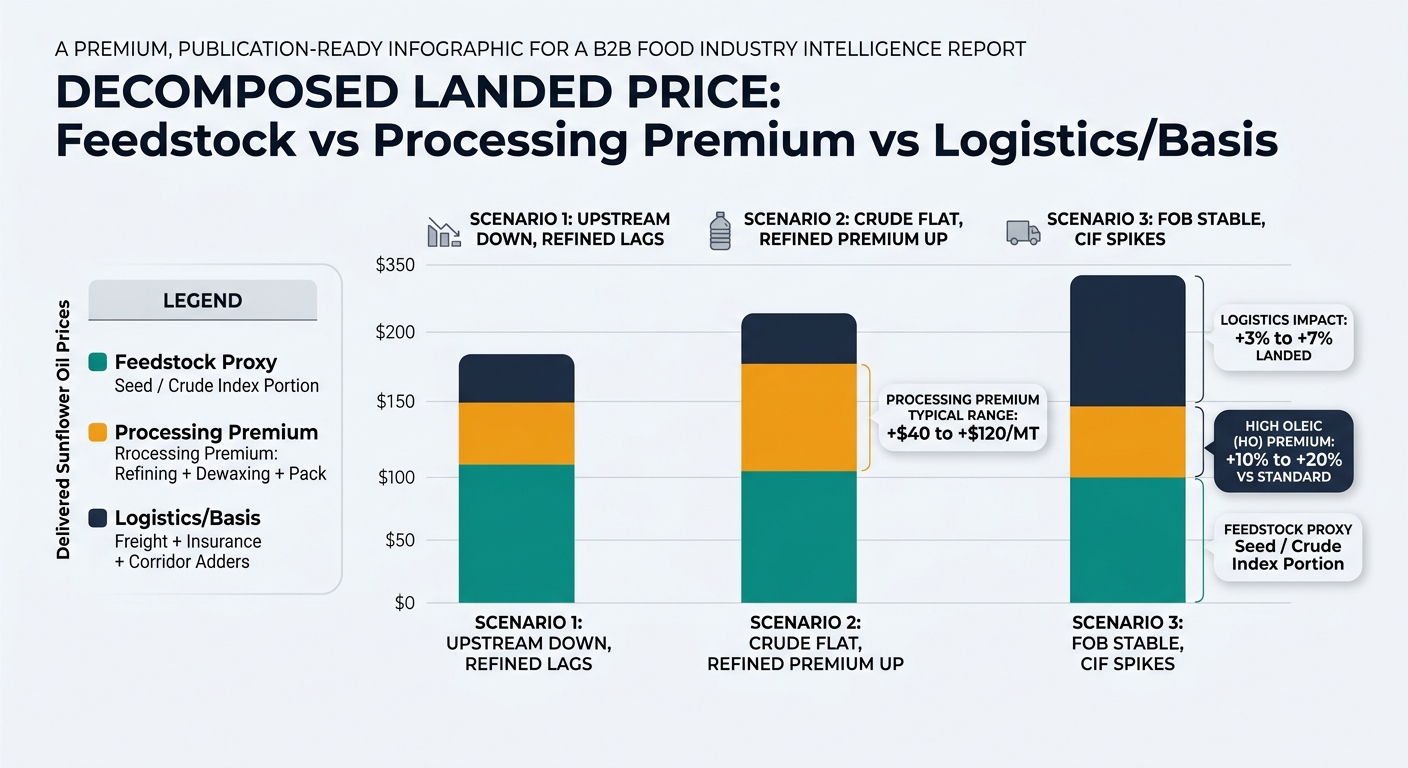
Procurement impact → Stop negotiating sunflower oil as one line item. Negotiate it as three markets:
Quick win: Ask for a dual quote: FOB (or ex-works) + a separately itemized delivered add-on. If the supplier refuses, that’s a signal they’re hiding margin inside “freight.”
What happens → Teams compare CIF/DDP offers across suppliers without decomposing freight, insurance, and processing premiums.
Why it fails → In volatile corridors, suppliers can keep the all‑in number “competitive” while expanding hidden premiums.
Hidden cost → A $60/MT unexplained refining premium on 2,000 MT/year is $120k—often larger than the “savings” you fought for on the base price.
Quick fix: Require quotes in component form (index proxy + premium + logistics). Make “unexplained premium” a scored penalty in award decisions.
What happens → Procurement fixes price to de-risk budget, but the real risk is deliverability (route, lead time, tank availability).
Why it fails → Fixed price doesn’t protect you from non-performance, demurrage, substitutes, or emergency spot buys.
Hidden cost → One missed vessel window can create expedite + demurrage + production disruption that dwarfs a 1–2% price improvement.
Quick fix: Use shorter coverage blocks (e.g., 2–4 months) with service-level clauses and pre-agreed alternates, rather than a single annual “set-and-forget.”
What happens → Teams assume HO is a modest uplift and accept supplier claims of “premium is market.”
Why it fails → HO is identity-preserved and allocation-driven; premiums can widen sharply when acreage shifts or contracts are undersigned.
Hidden cost → Paying a 15–20% uplift when you only needed partial functionality (blend tolerance) is a structural overpayment.
Quick fix: Run a quarterly “HO necessity check” with QA/R&D: confirm where HO is truly required vs where a blend or alternate oil is acceptable.
Insight → The goal isn’t predicting the exact bottom. It’s reducing variance vs. budget and avoiding forced buys.
Data → Typical before/after shifts we see when teams operationalize market + supplier signals:
| Capability you operationalize | Before (common) | After (intelligence-driven) |
|---|---|---|
| Quote coverage | 2–3 incumbents | 6–10 qualified options across 2–3 corridors |
| Pricing cadence | Quarterly snapshots | Weekly signals + trigger-based buys |
| Contract structure | Annual fixed “all-in” | Mix of spot + short coverage + indexed/premium transparency |
| Risk posture | “Supplier is reliable” | Corridor + supplier scorecards updated monthly |
Procurement impact (realistic outcome ranges):
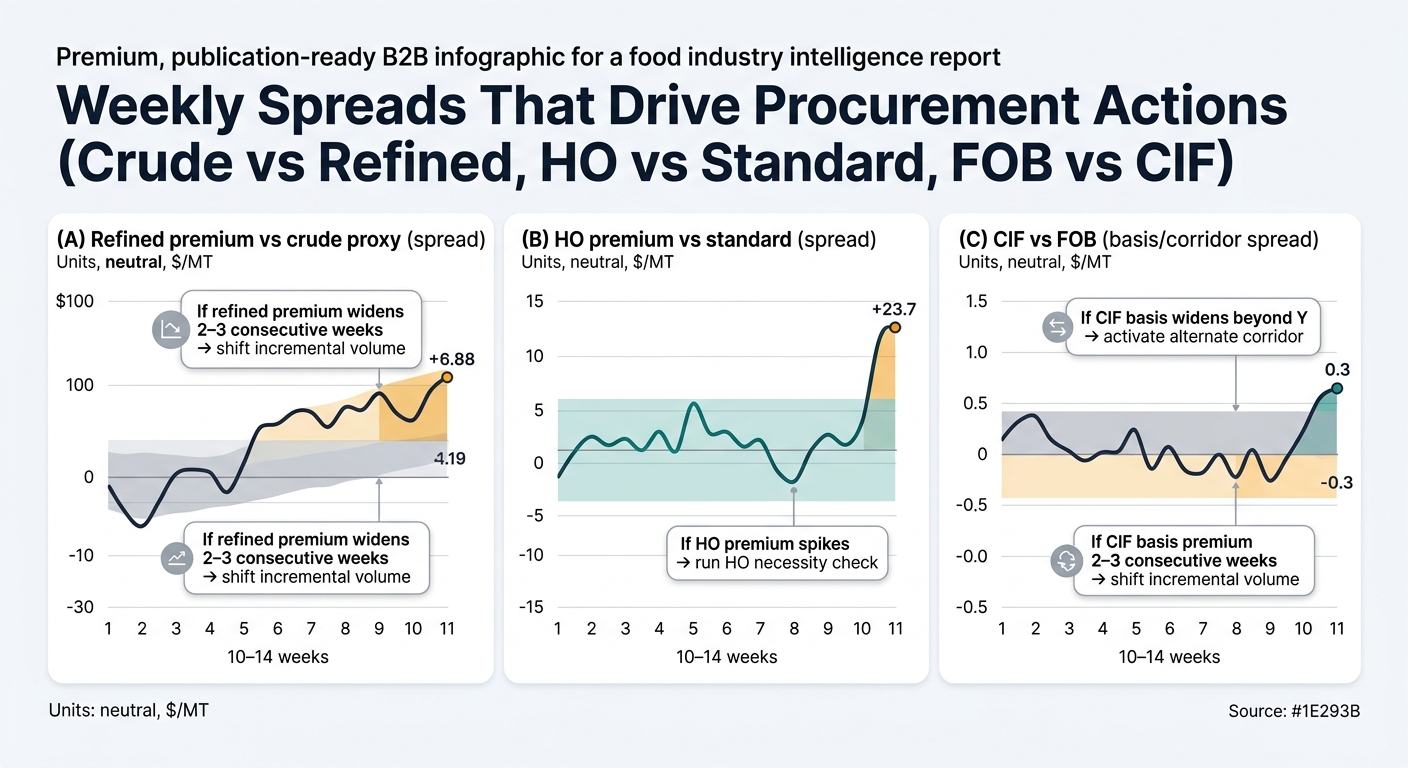
Quick win: Create a one-page “buying trigger” policy: when refining premium > X or CIF basis widens > Y, you shift volumes to alternate corridor or switch contract mode.
Insight → You’re negotiating in the premium layer, not the base.
Data → If crude proxies soften but refined offers don’t, you’re in an inventory/processing lag.
Procurement impact → Offer a two-step award: lock volume with a premium cap now, and reopen base pricing closer to shipment windows.
Insight → Landed cost is being set by route optionality.
Data → FOB looks stable while CIF moves fast.
Procurement impact → Activate pre-qualified alternates and negotiate Incoterms that shift controllable logistics back to you (only if you can execute).
Insight → Quality volatility often correlates with seasonal storage/handling stress.
Data → Claims rise even when price is stable—because suppliers are stretching lots.
Procurement impact → Tighten acceptance governance: require COA + retain samples + define price penalties for out-of-trend results. Use that to justify dual-sourcing even at a small premium.
Insight → Sunflower teaches a broader lesson: in edible oils, premiums and basis often matter more than the headline index.
Data → Similar patterns show up in:
Procurement impact → Build one operating model for oils: component pricing, trigger-based coverage, and corridor optionality.
Insight → If your team can consistently separate market move from supplier margin move, you stop donating budget to opacity.
Data → The same three levers repeat: lag, premium, logistics. Most teams track only one.
Procurement impact → The hard part isn’t negotiating harder—it’s having defensible, repeatable logic for when to:
Logical next step framing: The procurement challenge that decides winners is whether you can maintain a weekly view of spreads (crude vs refined, HO vs standard, FOB vs CIF) and turn those signals into pre-approved actions before suppliers reprice.
Insight: Don’t chase the lowest all‑in delivered quote. Instead, hold volume coverage steady while you renegotiate premium transparency: require suppliers to separate base feedstock proxy from refining/HO/logistics adders. When the refined premium widens faster than crude proxies for 2–3 consecutive weeks, shift incremental volume to the corridor/supplier offering the tightest disclosed premium (even if base is slightly higher). This captures savings from premium compression and reduces the risk of being forced into emergency buys when CIF basis spikes.

Start Making These Sourcing Decisions with Live Signals
Tridge Eye — The strategy playbook above works — but only with current data feeding it. Real-time price movements, supplier risk scores, and origin alerts turn these frameworks into daily competitive advantages.