This report is powered by Tridge Eye Data Intelligence.
Every data point, price signal, and supply risk insight in this analysis comes from the same platform that procurement and sourcing leaders worldwide rely on daily. As you read, consider what this level of market intelligence could do for your sourcing decisions.
Frozen mangosteen is a niche frozen fruit SKU where procurement outcomes are disproportionately driven by conversion yield, manual labor capacity, and cold-chain execution—not by “fresh fruit price” alone. This guide translates those realities into practical sourcing actions procurement leaders can run (supplier portfolio, contracting posture, spec governance, and risk triggers) so you can defend decisions to QA, Ops, and Finance.
(Analyzed at: Apr, 2026)
Insight: If you rely on Thailand-season production for IQF arils/segments, treat Q2–Q3 (roughly Apr–Sep) as the critical contracting/availability window and secure (1) capacity + (2) spec addendum + (3) temperature-record expectations before peak-season labor and freezer capacity tighten. Use a dual-source bench (primary + pre-qualified alternate) to convert “single-point seasonal risk” into a controlled switching option. The savings typically come from fewer quality/temperature claims, less rework, and reduced spot-buy premiums—not just a lower quoted $/kg.
Frozen mangosteen looks like a simple frozen fruit SKU, but it behaves like a seasonal, labor-constrained, cold-chain-dependent specialty ingredient.
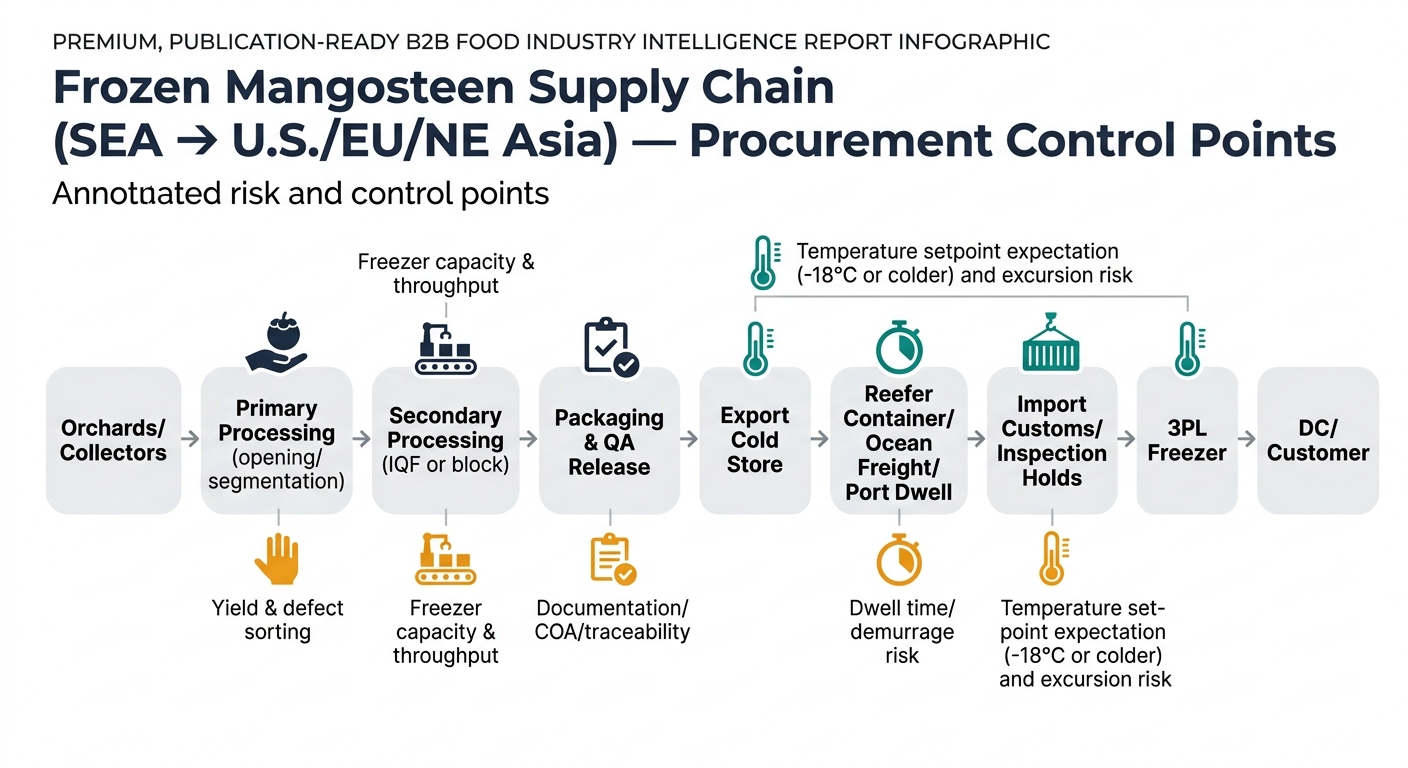
Below is the procurement-relevant truth: your negotiated $/kg is mostly a function of (a) usable yield and (b) labor + freezing capacity + reefer logistics, then only later “supplier margin.”
Key insight: The farmgate price you see is less about “commodity pricing” and more about crop quality + defect rate + timing inside the harvest curve.
Key insight: This is the economic heart of IQF arils. If your spec is strict (uniform segments, low defect tolerance), your “raw material cost per kg finished” can jump even if farmgate is flat.
Key insight:IQF is a capacity product (tunnels/spirals + throughput discipline). Block-frozen pulp is often a relief valve when aril specs or labor availability are constrained.
Key insight: For the U.S. and other high-scrutiny markets, the cost is not just packaging—it’s the documentation + verification readiness.
Key insight: Landed cost volatility often comes from dwell time, demurrage/detention risk, and reefer availability, not just base ocean rates.
Key insight: Distributor margin is visible and negotiable, but it’s usually not the root cause of volatility. The bigger levers sit upstream (yield, labor, capacity, cold chain).
Modeled as % of final delivered cost to a U.S. buyer DC. Actual ratios vary by origin, Incoterms, pack, seasonality, and service level. Use these as scenario starting points, not as “market averages.”
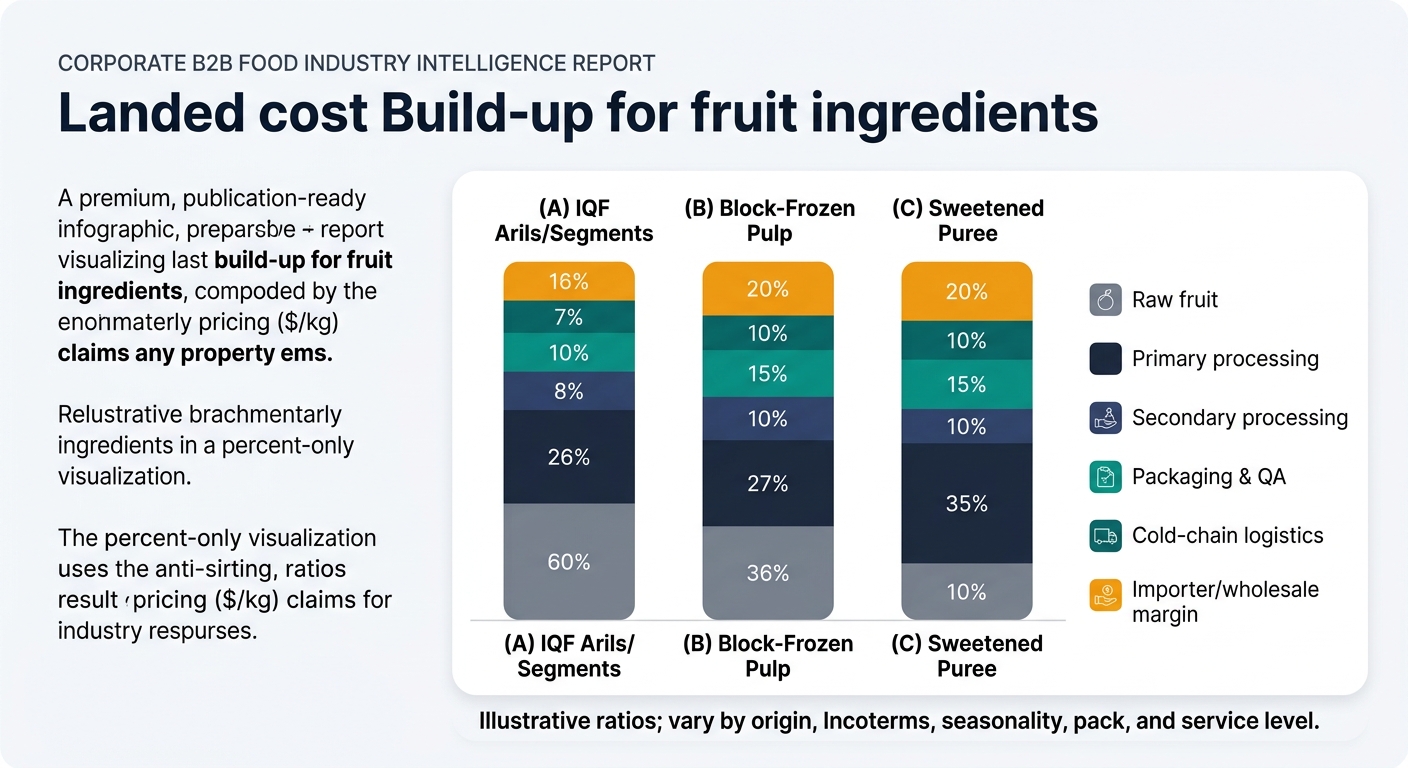
| Supply Chain Node | Cost Ratio (% of Final Cost) | What moves it most |
|---|---|---|
| Raw fruit (orchard/collector) | 25% | crop size + quality + timing |
| Primary processing (opening/yield/labor) | 30% | labor + yield + defect rate |
| Secondary processing (IQF freezing) | 12% | energy + throughput |
| Packaging & QA | 8% | barrier film + testing + rework |
| Cold-chain logistics (export→import) | 15% | reefers + dwell time + holds |
| Importer/wholesale margin | 10% | service level + financing |
| Supply Chain Node | Cost Ratio (% of Final Cost) | What moves it most |
|---|---|---|
| Raw fruit (orchard/collector) | 30% | crop economics |
| Primary processing | 18% | yield but less strict piece integrity |
| Secondary processing (pulping + block freeze) | 15% | energy + equipment |
| Packaging & QA | 7% | liners/cartons + COA |
| Cold-chain logistics | 18% | reefer + storage time |
| Importer/wholesale margin | 12% | inventory carry + demand variability |
| Supply Chain Node | Cost Ratio (% of Final Cost) | What moves it most |
|---|---|---|
| Raw fruit | 22% | quality/yield |
| Primary processing | 15% | yield + sorting |
| Secondary processing (puree/formulation) | 22% | inputs + processing time |
| Packaging & QA | 10% | drums/bags + testing |
| Cold-chain logistics | 16% | reefer + handling |
| Importer/wholesale margin | 15% | inventory + channel margin |
Frozen mangosteen is a “harvest-made, inventory-sold” category.
That means:
Procurement teams often expect frozen prices to track fresh fruit prices. In frozen mangosteen, the linkage is weak because the conversion economics dominate.
The disconnect happens when:
For U.S.-bound supply, importer obligations under FSMA FSVP require hazard analysis, supplier evaluation, and supplier verification activities (or documented alternatives), which adds governance work and can influence supplier selection and total landed cost. [2]
This is how procurement intelligence changes decisions without “feature dumping”—by tightening the few decisions that drive most outcomes.
Frozen mangosteen is a compact example of a broader procurement pattern: when conversion yield + cold chain + governance dominate, price-only buying fails.
Similar dynamics show up in categories procurement teams commonly manage alongside frozen fruit:
The transferable lesson: procurement intelligence is most valuable where the supply chain is fragile, not where it’s simple.
Frozen mangosteen forces clarity on the exact capabilities procurement leaders need to run resilient imported categories:
Make Faster, Data-Driven Sourcing Decisions
The insights in this report are just the starting point. Tridge Eye is the data intelligence solution that gives procurement and sourcing leaders real-time market signals, price benchmarks, and supply risk alerts — so you can act before the market moves.