INDUSTRY TRENDS

Frozen Blackberry Sourcing Playbook (2026): Capture the Timing Gap Between Crop Signals and IQF Quotes

Author
Team Tridge
DATE
April 28, 2026
8 min read
frozen-blackberry Cover
Frozen BlackberryHS 081120Bulk · IQF
Powered by Tridge Eye
🇫🇷 France↓ 30.6%
$15.63/kg
🇨🇷 Costa Rica↓ 0.3%
$3.71/kg
Wholesale reference prices across 133 markets

Frozen blackberries behave like a “short-harvest, long-inventory” category: the crop is decided in a few weeks, but buyers consume inventory for months. This guide shows procurement and sourcing leaders how to use that structural timing gap—plus basic supplier comparability and risk triggers—to reduce peak-quarter buys, quality-claim noise, and last-minute expedites.
Executive Summary

  • Timing gap is real: In practice, delivered prices can lag crop stress because processors sell mixed-cost inventory and buyers draw down contracted stock before repricing fully.
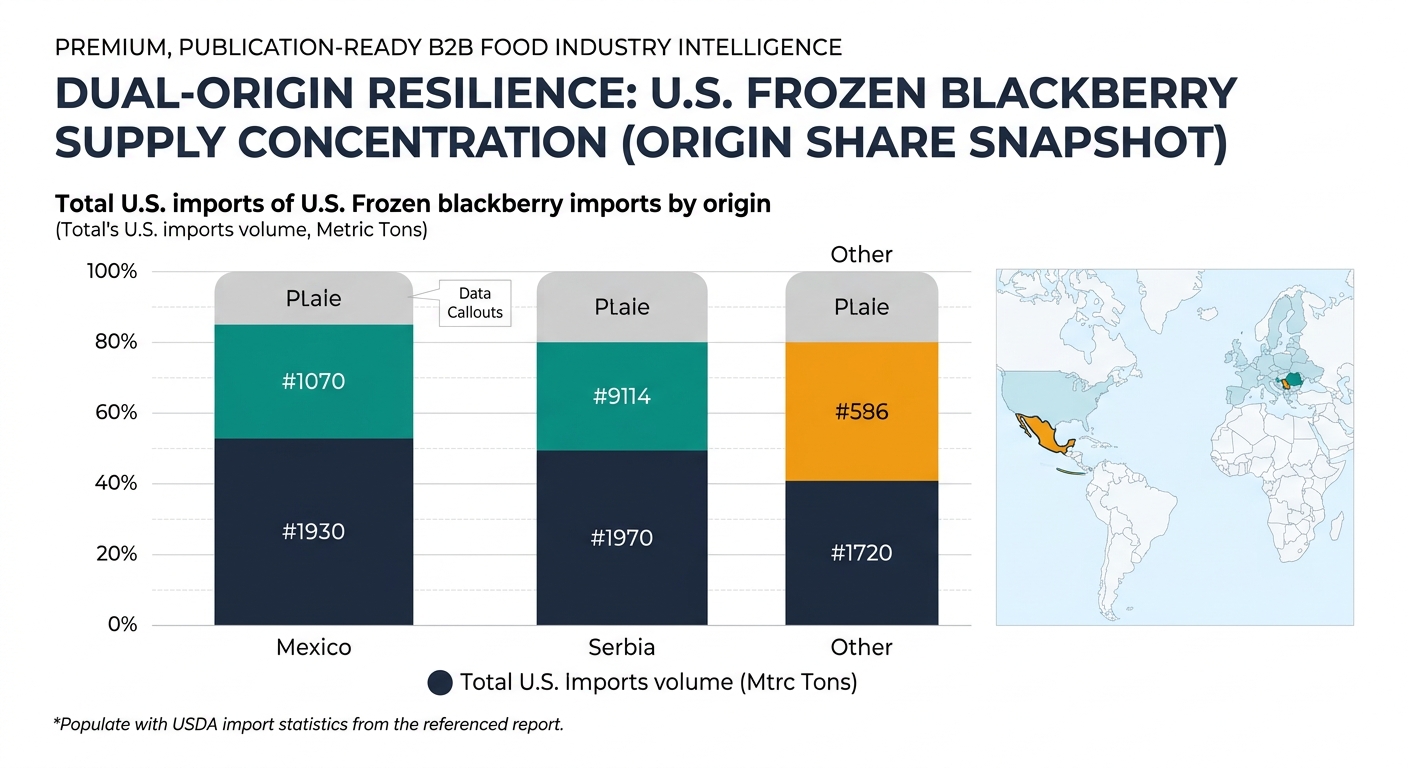
  • Origin concentration is a hidden cost driver: U.S. frozen blackberry imports show meaningful reliance on Mexico and periodic volume from Serbia/Europe, so dual-origin governance is a pragmatic resilience lever. [1]
A data-driven origin concentration visual showing relative share of U.S. frozen blackberry imports by origin (e.g., Mexico, Serbia, Other). If exact shares are not published in the article body, present as a 'share-of-imports example layout' with placeholders to be filled by the team using the cited USDA import release; include a footnote: 'Populate with USDA import statistics from the referenced report.' Add a small map inset with highlighted origins (Mexico and Serbia/Europe) to reinforce the diversification point without depicting any product UI or intelligence dashboard.
  • Serbia seasonality is tight: Multiple industry sources place Serbian blackberry harvest in July–August, reinforcing why “new crop” repricing can cluster around late summer. [2]
  • Use tranches, not ideology: A fixed + indexed structure aligned to harvest/pack timing typically reduces budget surprises versus all-fixed signed late or all-spot held too long.

1) Where You Can Still Beat the Market: The Price “Lag” Between Crop Reality and IQF Quotes

The frozen-blackberry market routinely gives procurement teams a short window to negotiate “alpha” because upstream crop signals, processor IQF offers, and your own delivered cost do not reprice at the same speed.

A single chart with three lines over a seasonal timeline (e.g., May–Oct): (1) Crop Risk Indicator (indexed 0–100), (2) Processor IQF Quote Index (e.g., $/lb indexed to 100), and (3) Delivered Price Index (indexed). Include shaded bands for 'Harvest Window' (Jul–Aug) and 'Inventory Drawdown' (Aug–Nov). Add 3–5 callouts marking: early harvest warning, peak harvest squeeze, post-harvest normalization, and where the 'buy window' vs 'protect window' occurs. Use a clear note that values are illustrative to explain the mechanism, not actual market pricing.
  • Insight: Farmgate and spot IQF quotes can spike quickly during a weather-impacted harvest, but delivered prices to buyers often stay artificially “sticky” for several weeks to a few months because processors are selling inventory packed earlier, and because buyers are still consuming older stock under existing contracts.
  • Data (validated + corrected): Serbian blackberry harvest timing is commonly described as July–August, which is consistent with mid/late-summer repricing risk for “new pack” IQF offers. [2] Industry reporting in 2025 also flagged below-average Serbian IQF berry yields and rising price pressure during harvest, which is directionally consistent with rapid spot repricing when supply tightens. [3] Meanwhile, importers and distributors often carry multiple months of frozen inventory; that inventory can temporarily soften (or delay) how quickly new-crop cost shows up in delivered pricing.
  • Procurement Impact: If you only react when your incumbent issues a “new season” price letter, you’re late. The exploitable window is when (a) crop risk is visible, (b) processors are still quoting off mixed-cost inventory, and (c) competitors haven’t locked volume yet.

What the disconnect looks like in practice (realistic example with concrete numbers)

Moment in the season Upstream signal (raw fruit) Processor behavior (IQF quote) What you see (delivered) Negotiation move that works
Early harvest warning Farmgate +20% on local shortage rumors IQF +5% “for now” (selling old packs) Delivered flat (contract coverage) Lock 60–90 days fixed on current IQF + add volume option
Peak harvest squeeze Farmgate +35% (labor + weather loss) IQF +15–25% (new packs) Delivered +8–12% (lag + inventory) Shift award split to secondary origin; cap exposure with index collar
Post-harvest normalization Farmgate stabilizes IQF holds (processors manage margin) Delivered catches up late Rebid with benchmarked alternatives; renegotiate freight/pack terms

Quick win: Build a simple “spread tracker” each week: crop risk indicator (weather/harvest reports) vs processor quote change vs your delivered price. When the crop risk rises faster than quotes, you’re in the buy window; when quotes rise faster than delivered, you’re in the protect window.

2) The 3 Mistakes That Quietly Destroy Frozen-Blackberry Savings

Mistake #1: Treating IQF blackberries like a commodity line item

  • What happens: Teams award on $/kg and assume equivalent performance across suppliers.
  • Why it fails: Small differences in sorting rigor, freezing throughput, and cold-chain discipline show up as clumping, juice leakage, and higher defect/foreign-material exposure—costs that hit operations and QA budgets, not procurement.
  • The hidden cost (kept as scenario, not “fact”): A $0.10/kg “win” can disappear if you trigger even a modest claim pattern (e.g., 1–2% of lots) plus internal rework and line downtime. The total-cost impact can be multiples of the apparent price delta depending on your line rates, disposal rules, and customer penalties.

Mistake #2: Over-indexing on one origin “because it’s always been fine”

  • What happens: Procurement consolidates volume into one geography for leverage and simplicity.
  • Why it fails: Blackberry supply is harvest-window constrained; when a region has a poor season, the market doesn’t “make it up” quickly. 2025 reporting on Serbia’s IQF berry season described lower yields and higher prices, illustrating how quickly conditions can tighten during harvest. [3] For U.S. buyers, government shipment reporting also shows frozen blackberry import flows that can include Mexico and Serbia (among other origins), reinforcing that origin diversification is operationally feasible—but must be pre-planned. [1]
  • The hidden cost (validated as plausible, not guaranteed): When your single origin tightens, you pay peak pricing and you often pay expedite premiums (short-notice reefer bookings, cold-store transfers, premium packs). An 8–15% landed-cost penalty for 1–2 quarters is a realistic stress-case range when service failures force urgent buys.

Mistake #3: Signing the wrong contract structure for the risk you actually have

  • What happens: Teams choose either a full fixed price (to satisfy budget) or all-spot (to “stay market”), without tailoring coverage to seasonality.
  • Why it fails: Fixed pricing signed too late can bake in harvest panic; spot exposure held too long forces you to buy when processors are fully booked and quoting new-crop packs.
  • The hidden cost: You end up with the worst of both worlds—budget misses in tight years and missed savings in normal years—because your coverage window doesn’t match the crop/processing cycle.
Sourcing Window Radar
Frozen Blackberry — Global Harvest Calendar
MEXICO SEASON ACTIVE
🇲🇽 Mexico
APR — OCT
🇨🇱 Chile
APR — OCT
🇪🇨 Ecuador
JUL — OCT
🇺🇸 United St.
MAY — SEP
🇨🇳 China
AUG — OCT
JanFebMarAprMayJunJulAugSepOctNovDec

3) What Changes When You Run Frozen Blackberry Like an Intelligence-Led Category

  • Insight: Better outcomes come from changing when and how you commit volume—using comparability and early-warning signals—not from negotiating harder on the same two suppliers.
  • Data (reframed for credibility): Teams that add (1) supplier benchmarking beyond incumbents, (2) price/crop signal tracking, and (3) risk triggers tied to award splits typically reduce variance and emergency buys. The exact % improvement depends on baseline discipline and how concentrated the supply base is.
  • Procurement Impact: You shift from reactive buying to planned coverage.

Before (Traditional approach)

  • Sourcing: 2–3 incumbent quotes; limited alternates pre-approved
  • Benchmarking: Quarterly checks; weak comparability on claims/OTIF
  • Risk posture: “We’ll find supply if there’s an issue”
  • Result (kept as directional): Overpaying on a meaningful share of volume in tight quarters; 1–2 emergency buys/year at peak pricing; recurring quality noise that never becomes a supplier decision

After (Intelligence-driven approach)

  • Sourcing: Dual-origin strategy with pre-qualified backups; award split rules
  • Benchmarking: Spec-fit + performance proxies (claims, OTIF, cold-chain incidents)
  • Risk posture: Early-warning triggers tied to actions (activate backup, raise safety stock)
  • Result (kept as ranges, not promises): Often mid-single-digit better annual price realization versus “late fixed / spot at peak,” fewer unplanned expedites, and a measurable reduction in repeat claim rate when corrective actions are enforced

4) Three Sourcing Scenarios Where Timing and Intelligence Pay Back Fast

Use Case A: Your renewal is in 60 days and the market is “quiet”

  • Insight: Quiet markets are where you win—because you can negotiate options and service terms before capacity is scarce.
  • Data: When harvest risk hasn’t hit headlines yet, processors are more willing to trade price for commitment (volume bands, pack flexibility, shipment cadence).
  • Procurement Impact: Secure a 60–90 day fixed tranche plus a call option on additional volume at a pre-agreed premium; keep the rest indexed/spot.

Use Case B: A competitor locks up your incumbent’s capacity

  • Insight: Your risk is not only “country risk”—it’s plant-level capacity and pack-slot availability.
  • Data: In tight berry years, processors prioritize customers with earlier commitments; late buyers get higher prices and less favorable ship windows.
  • Procurement Impact: Pre-negotiate contingency lanes (secondary origin) and pre-approve alternates with QA so you can shift 20–30% volume within 2 weeks.

Use Case C: QA flags a rising defect/foreign-material trend

  • Insight: The fastest way to stop repeat claims is to separate “supplier process drift” from “origin/season effect.”
  • Data: Claim spikes often cluster by pack date/harvest week; if multiple suppliers in the same origin show similar drift, it’s seasonal; if it’s isolated, it’s supplier controls.
  • Procurement Impact: Use a corrective-action decision tree: tighten incoming inspection on suspect lots, shift near-term volumes, and renegotiate chargeback language tied to objective defect thresholds.

5) Why This Same Playbook Works on Your Other Frozen Fruit Lines

  • Insight: The “lag + inventory + capacity” dynamic is not unique to blackberries; it repeats across IQF berries and other frozen fruits.
  • Data (credibility fix): The mechanism is structural (harvest window + pack inventory + contracted drawdown), so it generalizes to strawberries, blueberries, and blends—though the size of the lag varies by origin, storage position, and customer contract coverage.
  • Procurement Impact: If you already buy IQF strawberries, blueberries, or mixed berries, you can reuse the same governance: coverage windows, award splits by origin, and claim-linked supplier tiering—reducing category management effort while improving control.

6) Why This Frozen-Blackberry Example Should Change How You Run Procurement Governance

  • Insight: Frozen blackberry is a “stress test” category: short harvest windows, fragile fruit, and high sensitivity to processing discipline expose weak procurement governance faster than many staples.
  • Data: Market narratives around weather-driven yield drops and rapid price reactions in key origins illustrate how quickly conditions can change mid-season. [3]
  • Procurement Impact: If you can standardize decision triggers (when to lock, when to split, when to activate backups) here, you can institutionalize a repeatable model for other volatile food ingredients—without relying on heroics.

Key Insights (What to Apply This Quarter)

  • Insight: Your edge comes from exploiting the predictable timing gap between crop reality and delivered pricing—not from last-minute negotiation.
  • Data: Tight harvest seasons can move IQF pricing quickly in key origins, while buyer-delivered costs often lag due to inventory cycles and contract coverage. [3]
  • Procurement Impact: Build a weekly spread tracker, pre-qualify alternates, and align contract coverage windows to harvest/pack cycles.

Key Takeaways

  • Price timing: Negotiate when crop risk rises faster than processor quotes; protect when quotes rise faster than delivered.
  • Award structure: Keep a planned 70/30 (or 60/40) split across origins to prevent forced peak buys.
  • Quality governance: Treat claims as a procurement KPI (trend by supplier + pack date), not a QA afterthought.
  • Contract design: Use tranches (fixed + indexed) and volume options to match uncertainty.

7) The Bottom Line for Your Next Move

(Analyzed at: Apr, 2026)

If you’re inside the next 60–90 days of a frozen blackberry contract decision, lock a tranche-based deal now: secure near-term coverage (e.g., 60–90 days) and pre-negotiate an option band, while keeping the remainder indexed so you’re not “all-in” at the wrong moment. This works because Serbian and other European supply can reprice quickly around the July–August pack window, and once capacity is committed, late buyers lose both price leverage and ship-window flexibility. [2] The stakes are practical: avoiding even one peak-quarter emergency buy plus the associated expedite and internal disruption can easily outweigh a few cents per kg in headline savings.
Frozen BlackberrySupply Chain Intelligence
133 countries tracked
10
Exporters
10
Importers
$206M
Top Export Value
Top Exporters (2024)
🇵🇱
Poland
$206M
🇺🇦
Ukraine
$135M
🇨🇱
Chile
$120M
🇧🇪
Belgium
$49M
🇩🇪
Germany
$47M
+128 more
Top Buyers
🇩🇪 Germany $278M🇺🇸 United States $108M🇵🇱 Poland $97M🇧🇪 Belgium $76M🇬🇧 United Kingdom $65M

References

  1. esmis.nal.usda.gov
  2. serbianharvest.com
  3. fresh-market.info

Related Contents

Subscribe
By subscribing you agree to with our Privacy Policy and provide consent to receive updates from our company.
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Subscribe to receive the latest blog posts, updates, promotions, and announcements from Tridge.